1. The four FTX silos
The first-day presentation gave the administrators a working map for locating, preserving and recovering assets across a complex corporate group. It described four broad clusters:
- WRS Silo: U.S. businesses including FTX US, LedgerX and FTX Capital Markets.
- Alameda Silo: Alameda Research and related entities.
- Dotcom Silo: FTX.com and international exchange operations.
- Ventures Silo: Venture investments and acquired businesses.
These labels help explain the structure of the case. They do not, on their own, determine which estate owes a particular creditor or the amount ultimately payable.
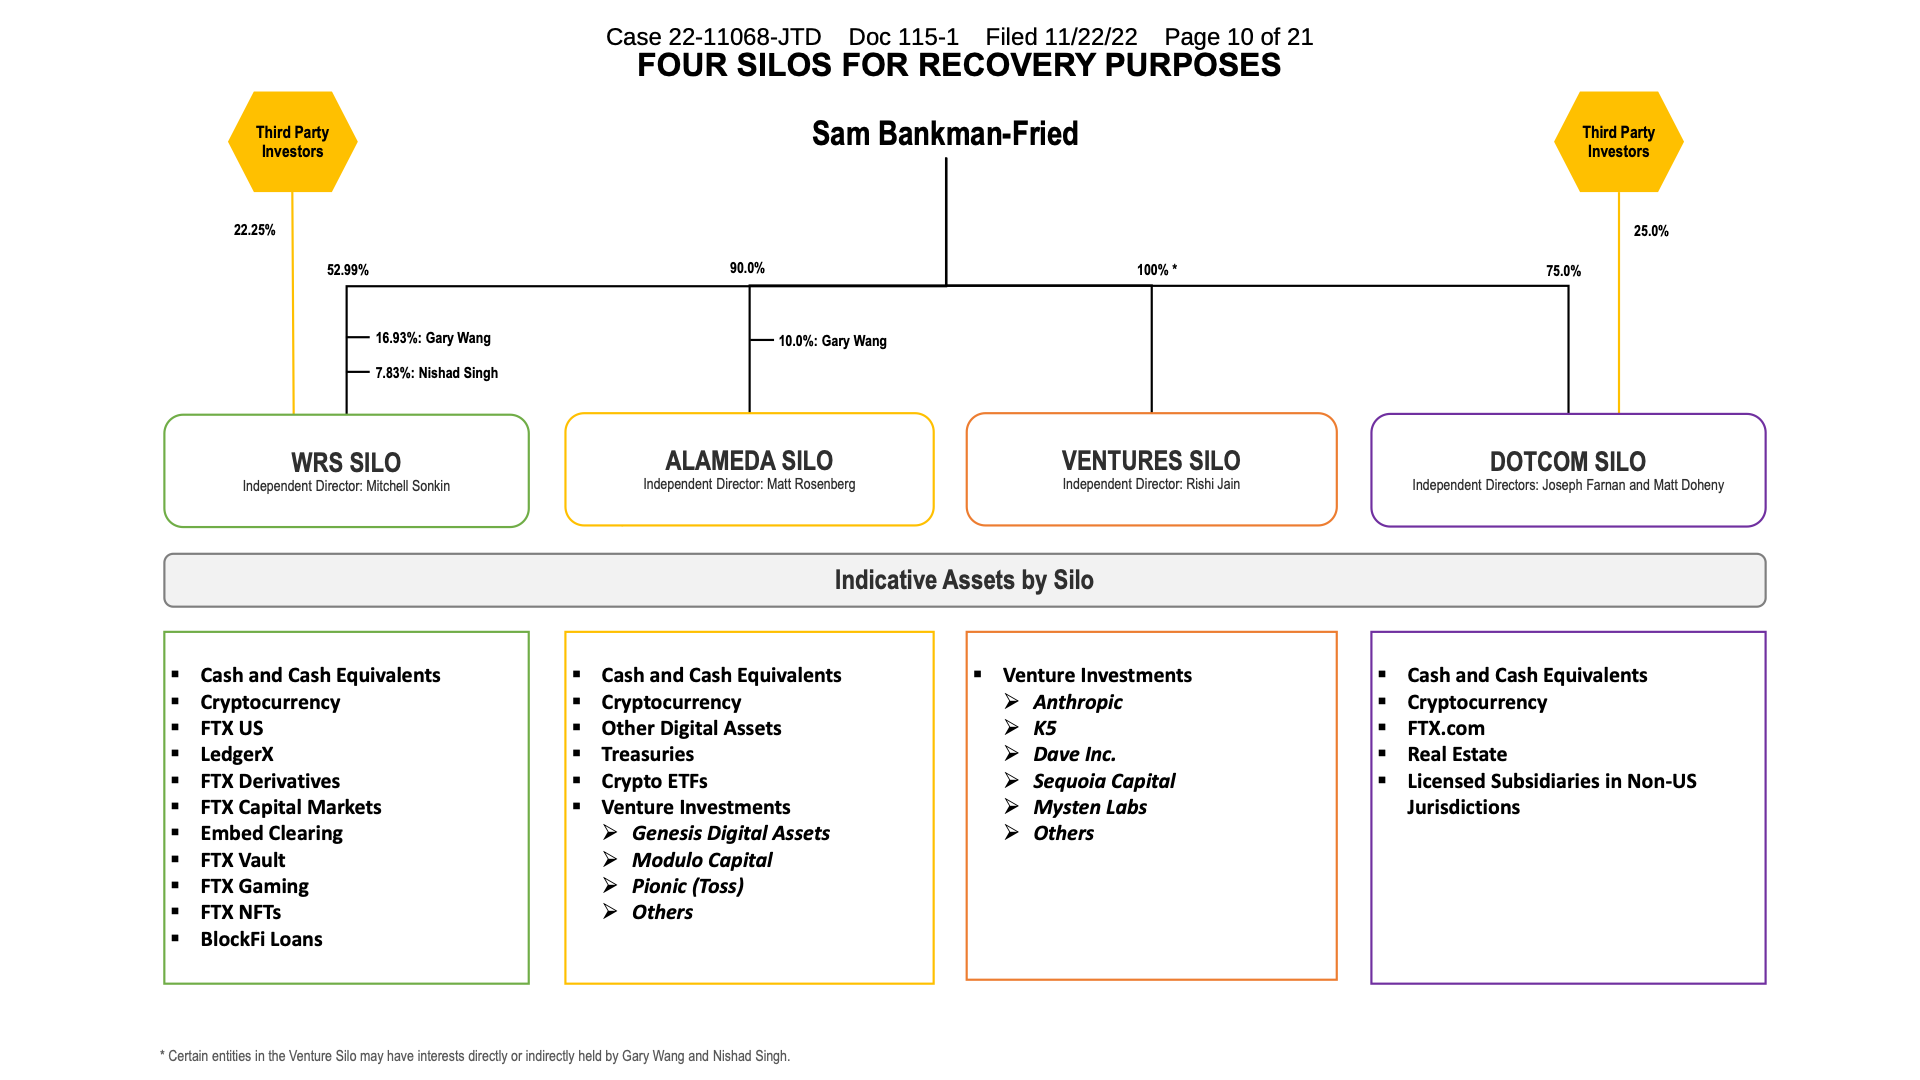
Court materials, pages 1 and 10: The presentation cover and organizational chart.
2. Inside the Ventures Silo
Page 12 of the presentation lists investments and interests held across the group. They range from artificial intelligence and blockchain companies to mining businesses and investment funds. The existence of an interest in a company does not establish its eventual sale price, net proceeds or allocation among estates.
3. Venture gains and the payment gap
During his criminal proceedings, Sam Bankman-Fried pointed to the potential value of venture assets when disputing the scale of customer losses. That argument did not change the legal findings concerning the unauthorized use of customer funds. A valuable investment and a breach of trust can coexist.
Anthropic is the most widely cited example. FTX’s estate sold its interest in two transactions in 2024 for a reported total of about $1.3 billion. That transaction strengthened the estate’s resources, but a creditor’s recovery still depends on the relevant plan, allowed claim, distribution rules and any applicable offsets or taxes.
2026 reality: cash in the estate is not an instant payout
Asset realization is one step in a broader bankruptcy process. Administration, objections and distribution procedures may continue after a sale.
Data as of August 2026: according to the FTX Recovery Trust, after the fifth distribution on July 31, 2026, FTX.com and FTX US customers (Classes 5A and 5B) have received a cumulative 105% of their allowed claims, and total distributions have approached
2026 reality: cash in the estate is not an instant payout
Asset realization is one step in a broader bankruptcy process. Administration, objections and distribution procedures may continue after a sale.
0 billion. Timing and amounts for each creditor depend on KYC and claim status.Check your own case: The U.S. and Bahamas proceedings, KYC/AML requirements, claim objections and tax questions can affect timing and eligibility. A documentation problem is not automatically a forfeiture; its effect depends on the applicable rules and notice.
4. Assessing your options
A creditor can generally choose to wait for distributions or explore a transfer of the claim. The right choice depends on the claim’s status, the price offered, rights being transferred, expected timing, fees and tax consequences. Compare an offer with your own circumstances rather than a universal recovery percentage.
How a claim purchase may proceed
Reclaim Capital’s perspective
Selling a claim can exchange uncertain future distributions for a known price today. It can also mean giving up future upside. Review the agreement and, where appropriate, seek independent legal and tax advice before deciding.
Have an FTX claim?
Tell us about your claim to discuss a possible offer. An enquiry does not oblige you to sell.
Frequently asked questions
Where did the FTX estate obtain funds for recoveries?
Why can distributions take time after an asset sale?
Can I sell an FTX bankruptcy claim?
Prepared by Reclaim Capital. We work with distressed claims and complex recovery situations.
This article is informational and draws on public court materials. It is not legal, tax or investment advice; outcomes depend on the individual claim and applicable proceedings.
Contact: @ReclaimCapital

